
Auditing has always depended on evidence.
An auditor needs to establish whether transactions happened, whether records are accurate, whether controls worked and whether financial statements give a fair picture of an organisation’s activities.
Traditionally, much of this work happens after transactions have already taken place.
An auditor collects records, checks supporting documents, reconciles balances, confirms transactions and tests samples. If the organisation has multiple systems, the auditor may also have to compare information from different databases to establish whether the records agree.
Blockchain introduces a different possibility.
Instead of relying entirely on records held separately by different parties, organisations can use a shared digital ledger where transactions are recorded, time-stamped and linked cryptographically.
This can give auditors a more direct view of transaction histories.
It doesn’t eliminate auditing.
It changes what auditors can access, how they verify evidence and how quickly they can identify problems.
1. What Is Blockchain Auditing?
Blockchain auditing is the use of blockchain technology and blockchain-based records as part of an audit or assurance process.
It can involve two related activities.
The first is auditing transactions and records that exist on a blockchain.
The second is using blockchain technology to improve the audit process itself.
These are different.
An auditor examining a cryptocurrency business, for example, may need to verify digital-asset balances and transactions recorded on a blockchain.
Another organisation may use a permissioned blockchain to record supply-chain transactions, payments or intercompany activities. An auditor could use those records as part of the audit evidence.
Blockchain can also support audit systems that automatically monitor transactions and flag certain conditions.
The technology therefore affects both the subject being audited and the way auditing can be performed.
2. Why Does Blockchain Matter to Auditors?
Traditional auditing often involves working backwards.
A transaction happened months ago.
The organisation has a record of it.
The auditor then collects supporting evidence and determines whether the transaction was recorded correctly.
Blockchain can bring some transaction information closer to the point where the activity occurs.
Because blockchain records can be shared and synchronised across authorised participants, auditors may be able to access transaction information in a more consistent format. IFAC has identified this as one of blockchain’s potential effects on the accounting profession, including opportunities for more continuous auditing rather than relying entirely on periodic reviews.
This doesn’t mean every audit becomes real-time.
It means the technology makes real-time or near-real-time assurance more practical in some environments.
3. How Blockchain Works as an Audit Trail
An audit trail is a record showing how a transaction or piece of information moved through a system.
Consider a company purchasing equipment.
The process might look like this:
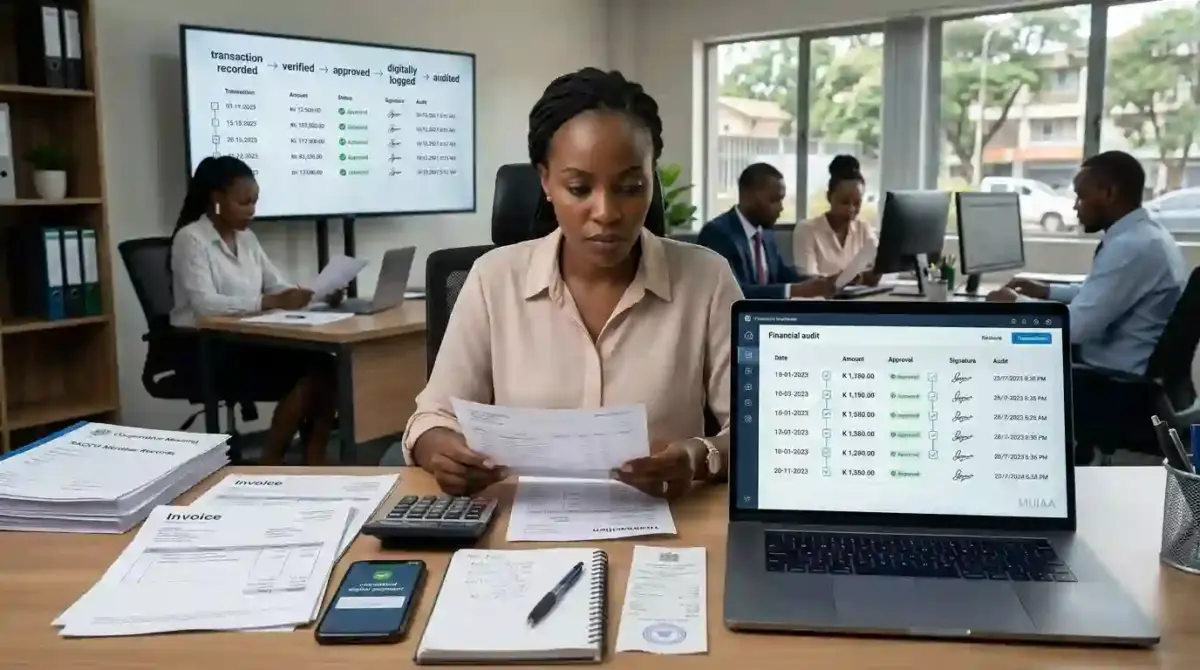
Purchase request → approval → supplier invoice → payment → accounting entry → asset record
In a traditional system, information about each stage may exist in different systems.
An auditor has to bring the information together.
With a blockchain-supported system, relevant events can be recorded in a shared ledger.
The auditor may then be able to follow the transaction through a connected history.
Blockchain’s use of timestamps, cryptographic links and distributed records can make unauthorised alteration of recorded data more difficult and easier to detect. Recent research on blockchain in auditing identifies data integrity and traceability as major potential benefits. (Frontiers)
That can strengthen the evidence available to an auditor.
4. Blockchain and Traditional Auditing
Traditional auditing is not disappearing.
The difference is in how evidence can be collected and verified.
| Traditional auditing | Blockchain-supported auditing |
|---|---|
| Records collected from different systems | Shared ledger can provide common transaction records |
| Reconciliations often required | Some transaction-level reconciliation can be reduced |
| Significant retrospective testing | Greater potential for continuous monitoring |
| Evidence may be collected in batches | Transaction data can be available closer to real time |
| Manual confirmation may be required | Blockchain records can provide direct transaction evidence |
| Auditor analyses historical records | Auditor can analyse transaction histories continuously |
This doesn’t mean blockchain makes the right-hand column automatic.
Integration, permissions, data quality and controls still matter.
IFAC specifically notes that blockchain may reduce the need for some transaction-level reconciliations, but professional expertise is still needed to assess complex accounting transactions.
5. Blockchain and Audit Evidence
Audit evidence is information used by an auditor to reach a conclusion.
This could include:
- Invoices
- Contracts
- Bank statements
- Receipts
- Transaction records
- Confirmations
- Accounting entries
- Inventory records
- Payroll records
- System logs
Blockchain can add another source of evidence.
Suppose a company records a payment on a blockchain.
The auditor may be able to verify:
- The transaction
- The timestamp
- The wallet or account involved
- The transaction amount
- The transaction history
- The blockchain confirmation
- Related transactions
This can be useful because the auditor isn’t relying solely on a screenshot or spreadsheet provided by the organisation.
However, there is an important limitation.
A blockchain can prove that data was recorded. It doesn’t automatically prove that the original information was true.
If someone enters false information into a blockchain, the blockchain can preserve that false information very effectively.
Recent research identifies this “garbage in, garbage out” problem as one of the key limitations of blockchain auditing. (Frontiers)
6. The “Garbage In, Garbage Out” Problem
Imagine a company receives 500 units of a product.
An employee enters:
Quantity received: 5,000 units.
The blockchain records the 5,000 figure.
The record is now difficult to alter.
But that doesn’t make 5,000 the correct number.
The auditor still needs evidence that the physical goods actually existed.
This could involve:
- Physical inspection
- Supplier documentation
- Shipping records
- Warehouse records
- Independent confirmations
- IoT or sensor data
- Other supporting evidence
Blockchain strengthens the integrity of the recording layer.
It doesn’t automatically establish the truth of every real-world event.
That distinction is critical when discussing blockchain auditing.
7. How Blockchain Can Improve Audit Efficiency
Auditors spend significant time collecting and reconciling information.
Blockchain can reduce some of that work where participating organisations use a shared ledger.
For example, imagine two companies that regularly trade with each other.
Company A records:
Invoice: KSh 5 million
Company B records:
Payable: KSh 5 million
Traditionally, auditors may need to reconcile the two records.
A shared blockchain system could allow both parties to work from the same underlying transaction record.
That can reduce duplicate data entry and some reconciliation work.
IFAC has highlighted this shared-record capability as one of the ways blockchain could improve accounting and auditing efficiency
8. Blockchain and Continuous Auditing
One of the most interesting applications is continuous auditing.
Traditional audits often happen at specific intervals.
An organisation may prepare annual financial statements, and auditors then examine the relevant records.
Blockchain makes it possible to monitor transactions much closer to when they occur.
For example, an automated audit system could monitor:
- Large transactions
- Unusual payment patterns
- Duplicate transactions
- Transactions outside approved limits
- Changes in ownership
- Smart-contract activity
- Unusual wallet activity
An exception could then be flagged for human review.
This changes the role of the auditor.
Instead of discovering every issue months after it happened, some risks can be identified much earlier.
Recent professional guidance from ISACA argues that blockchain environments may require more continuous monitoring of transactions, validator behaviour and smart-contract execution rather than relying only on periodic assurance.
9. Smart Contracts and Auditing
Smart contracts introduce another important audit area.
A smart contract is software that automatically executes predefined rules.
For example:
If payment is received and all approval conditions are satisfied, release the funds.
The advantage is automation.
The audit challenge is that the software itself becomes part of the control environment.
An auditor may therefore need to examine:
- The contract’s code
- The rules it implements
- Who deployed it
- Who can modify it
- What permissions exist
- Whether the contract was tested
- Whether transactions followed the programmed rules
A smart contract can execute perfectly while implementing a poorly designed rule.
That means auditors need to understand both the financial process and the technology behind it.
10. Blockchain Auditing and Fraud Detection
Blockchain is often presented as a way to prevent fraud.
That needs some qualification.
Blockchain can make certain forms of record manipulation harder because previously recorded information is designed to be difficult to change without detection.
It can also provide a detailed transaction history.
This can help auditors identify unusual activity.
For example:
- Repeated transactions
- Unusual transaction timing
- Transfers outside normal patterns
- Unexpected changes in balances
- Unauthorised transactions
- Suspicious relationships between accounts
But blockchain doesn’t automatically detect fraud.
An auditor still needs analytical procedures, controls, investigation and professional judgment.
Research on blockchain auditing identifies improved traceability and transparency as potential benefits, while also noting that blockchain alone cannot eliminate fraud risk.
11. Blockchain and Financial Statement Audits
Financial statement audits involve determining whether financial information is fairly presented according to the relevant accounting framework.
Blockchain can support parts of this process.
For example, if a company’s transactions are recorded on a permissioned blockchain, auditors may be able to access a consistent transaction history.
This can support testing of:
- Revenue
- Purchases
- Payments
- Receivables
- Payables
- Inventory movements
- Digital assets
- Intercompany transactions
The auditor still has to consider accounting treatment.
A blockchain transaction doesn’t automatically tell the auditor how that transaction should be recognised in the financial statements.
Technology provides evidence.
Accounting standards and professional judgment determine how that evidence should be interpreted.
12. Blockchain Auditing of Digital Assets
Digital assets create a particularly clear use case.
When assets exist directly on a blockchain, auditors can inspect transaction histories without relying entirely on a company’s internal database.
For example, an auditor examining a cryptocurrency holding may need to establish:
- What assets the organisation controls
- Which addresses belong to the organisation
- The balance held
- Transactions during the reporting period
- Transfers in and out
- Whether restrictions apply
- Whether third-party custodians are involved
However, even here, technical risks remain.
ICAEW notes that auditors need to consider issues around IT controls, blockchain nodes, blockchain explorers and the reliability of data extraction. An auditor may use their own node or a third-party infrastructure provider, with different benefits and risks in each approach.
13. Permissioned Blockchains and Auditing
Public blockchains aren’t the only option.
Businesses can also use permissioned blockchain networks where participants are known and access is controlled.
This can be useful for:
- Banks
- SACCOs
- Cooperatives
- Insurance companies
- Supply chains
- Government systems
- Corporate groups
A permissioned network can allow authorised participants and auditors to access relevant records without exposing sensitive information publicly.
For an auditor, this can create a controlled environment where transaction data is shared among defined participants.
The access model itself then becomes something that needs to be audited.
Who can write to the ledger?
Who can read it?
Who can approve transactions?
Who controls the network?
Who can change the software?
These are governance questions as much as technical ones.
14. Blockchain Auditing and Access Controls
Blockchain doesn’t remove the need for access controls.
In fact, access controls become even more important.
Consider a financial system where five people can approve transactions.
The auditor may need to verify:
- Who those users are
- What permissions they have
- Whether permissions are appropriate
- Whether credentials are protected
- Whether privileged access is monitored
- Whether access is removed when someone leaves
A blockchain may preserve the transaction history, but weak credentials can still create serious problems.
ISACA’s recent discussion of blockchain auditing highlights this shift, noting that established control frameworks remain relevant while access control and key management become particularly important in blockchain environments.
15. Blockchain and Audit Trails in Financial Institutions
Financial institutions process huge volumes of transactions.
Banks, SACCOs and other financial organisations therefore need reliable records and strong controls.
Blockchain can potentially support shared transaction histories between institutions.
Consider a loan.
The lifecycle could be:
Application → assessment → approval → disbursement → repayment → settlement
If important events are recorded in a blockchain-backed system, an auditor can potentially trace the loan throughout its lifecycle.
This can help identify:
- Missing approvals
- Unusual changes
- Duplicate transactions
- Late entries
- Incorrect balances
- Unauthorised activity
For African financial institutions, this could become particularly useful where organisations are connecting mobile money, banking and digital financial systems.
16. Blockchain Auditing for SACCOs and Cooperatives
SACCOs and cooperatives are another interesting application area.
They manage member contributions, loans, repayments, dividends, expenses and other financial activities.
A blockchain-backed audit trail could record important events across these processes.
For example:
Member contribution → transaction record → allocation → ledger entry → statement
Or:
Loan application → guarantor approval → loan approval → disbursement → repayment → settlement
An auditor could then trace the history rather than relying entirely on separate spreadsheets and documents.
This connects directly with the broader work MUIAA is doing around blockchain-based financial infrastructure and products such as ChamaConnect.
The important point is that blockchain becomes useful when it solves a real record-keeping or verification problem.
17. Blockchain Auditing and Supply Chains
Auditing doesn’t only involve financial transactions.
Supply chains also generate large amounts of information.
A blockchain can record events such as:
- Product origin
- Shipment
- Transfer of ownership
- Warehouse receipt
- Delivery
- Inspection
- Payment
An auditor can then trace the recorded history.
For example, a company claiming that a shipment came from a particular supplier could provide a transaction history showing the movement of that product through the supply chain.
But again, the physical world remains important.
If someone records false information about the quantity or quality of goods, blockchain preserves the record without proving the physical claim was true.
This is why blockchain auditing still needs external evidence.
18. Blockchain and Real-Time Audit Evidence
One major difference between blockchain and traditional record systems is timing.
A traditional audit may depend heavily on records produced after a reporting period.
Blockchain can make transaction information available much earlier.
That creates the possibility of:
Transaction → verification → monitoring → exception → investigation
instead of:
Transaction → months pass → audit → reconciliation → investigation
This doesn’t mean every transaction needs a human auditor watching it live.
Technology can handle routine checks while auditors focus on exceptions and areas requiring professional judgment.
19. Can Blockchain Replace Auditors?
No.
This is one of the biggest misconceptions surrounding blockchain auditing.
Blockchain can automate some parts of evidence collection, reconciliation and transaction testing.
It cannot replace professional judgment.
Auditors still need to assess questions such as:
- Is the transaction economically real?
- Is the accounting treatment appropriate?
- Are controls working?
- Is management’s estimate reasonable?
- Is the information complete?
- Are there risks outside the blockchain?
- Does the evidence support the audit conclusion?
A blockchain can show that a transaction occurred on a particular ledger.
An auditor still has to understand what that transaction means.
20. What Auditors Need to Understand About Blockchain
Auditors working with blockchain systems increasingly need both accounting and technology knowledge.
Important areas include:
20a. Distributed ledgers
How the network stores and validates information.
20b. Cryptography
How hashes, digital signatures and keys protect transactions.
20c. Consensus mechanisms
How network participants agree on valid transactions.
20d. Smart contracts
How automated rules execute transactions.
20e. Wallets and keys
How digital assets and transaction permissions are controlled.
20f. Network governance
Who controls the blockchain and how changes are approved.
20g. Data extraction
How auditors obtain reliable blockchain data.
20h. Application controls
How blockchain connects with accounting and business systems.
This is why blockchain auditing isn’t simply traditional auditing with a new database.
The auditor has to understand the technology that produces the evidence.
21. The Risks of Blockchain Auditing
Blockchain provides useful controls, but it introduces new risks.
21a. Data entered incorrectly
Blockchain doesn’t validate every real-world fact.
21b. Private key loss
Losing a private key can create serious access problems.
21c. Smart-contract errors
A coding mistake can cause an automated process to behave incorrectly.
21d. Network attacks
Certain blockchain architectures can be exposed to attacks that affect transaction integrity.
21e. Privacy
Not every audit record should be visible to everyone.
21f. Integration problems
Blockchain systems still need to connect with ERP, accounting, banking and other systems.
21g. Scalability
Large organisations may generate more data than a blockchain network can efficiently process or store.
21h. Regulatory uncertainty
Audit standards and regulations need to address how blockchain-based evidence should be treated.
Recent research continues to identify scalability, interoperability, privacy, regulatory alignment and technical skills as important barriers to blockchain adoption in auditing. (Frontiers)
22. Blockchain Immutability Is Not the Same as Accuracy
This deserves its own section because it is easy to get wrong.
Suppose an accountant enters:
KSh 10 million
when the correct amount is:
KSh 1 million.
If the incorrect figure is recorded on a blockchain, the blockchain’s resistance to alteration doesn’t make the number correct.
It simply makes the recorded entry harder to change.
The auditor still needs to establish whether the original transaction was accurate.
This is why blockchain should be viewed as an evidence and integrity mechanism, not an automatic truth machine.
23. Blockchain and Audit Automation
Smart contracts and automated analytics can take some routine audit procedures further.
A system could automatically test whether:
- A payment exceeded an approved limit
- A transaction lacked required approval
- A supplier received duplicate payments
- A loan exceeded an established limit
- A transaction occurred outside an approved period
- A required condition wasn’t met
The system could then flag the exception.
The auditor investigates the exception.
This creates a useful division of labour.
Software handles repetitive checks.
Auditors handle interpretation and judgment.
That model is likely to become increasingly important as audit systems combine blockchain with analytics and artificial intelligence.
24. Blockchain Auditing and Artificial Intelligence
Blockchain and AI solve different problems.
Blockchain is useful for creating structured, traceable transaction records.
AI is useful for analysing large volumes of information and identifying patterns.
Together, they could support more advanced audit systems.
For example:
Blockchain
Provides the transaction history.
↓
AI
Analyses the transactions.
↓
Risk engine
Flags unusual behaviour.
↓
Auditor
Investigates and makes a professional judgment.
Recent research identifies the combination of blockchain with AI and data analytics as an emerging direction for continuous monitoring, fraud detection and risk analysis. (Frontiers)
This doesn’t make the audit fully automatic.
It gives auditors better tools for deciding where human attention is needed.
25. How a Blockchain-Based Audit Could Work
A simplified process might look like this:
25a. Audit authorisation
The auditor receives authorised access to the relevant blockchain environment.
25b. Data access
Relevant transaction records are extracted directly from the blockchain or through approved infrastructure.
25c. Data validation
The auditor evaluates whether the blockchain data and surrounding systems are reliable.
25d. Transaction analysis
Transactions are analysed for completeness, unusual patterns and compliance with relevant rules.
25e. Smart-contract testing
Where smart contracts are involved, their logic and controls may also be assessed.
25f. External evidence
Auditors verify information that exists outside the blockchain.
25g. Professional judgment
The auditor interprets the evidence and reaches conclusions.
25h. Audit reporting
Findings are documented and reported according to the applicable auditing requirements.
This is broadly consistent with recent research proposing blockchain-based audit processes built around authorised data access, evidence collection, analysis and audit execution.
26. Blockchain Auditing vs Traditional Auditing
| Area | Traditional Auditing | Blockchain-Supported Auditing |
|---|---|---|
| Transaction records | Often collected from separate systems | Can come from a shared ledger |
| Reconciliation | Often significant | May be reduced for shared transactions |
| Audit timing | Often periodic | Greater potential for continuous monitoring |
| Evidence | Documents and system records | Blockchain records plus external evidence |
| Traceability | Depends on available records | Transaction history can be highly traceable |
| Automation | Increasing through audit software | Can combine blockchain with smart contracts |
| Fraud detection | Sampling and analytical procedures | Greater potential for continuous transaction analysis |
| Professional judgment | Essential | Still essential |
| External evidence | Essential | Still essential |
| System risk | Centralised-system risks | Blockchain, key, smart-contract and network risks |
The blockchain model changes the evidence environment.
It doesn’t remove the fundamental responsibilities of an auditor.
27. Blockchain Auditing Standards Are Still Developing
The technology is moving faster than some traditional audit frameworks.
That creates questions around:
- Evidence
- Data ownership
- Access
- Responsibility
- Smart-contract controls
- Network governance
- Privacy
- Error correction
- Regulatory compliance
This is an active area of standards development.
For example, ISO currently has a committee draft, ISO/CD TS 23353.2, covering auditing guidelines for blockchain and distributed ledger technology systems. The draft addresses blockchain audit principles, risks, control objectives and audit programmes. It is still under development, so it should not be treated as a final international standard.
This shows that blockchain auditing is moving toward more formal frameworks while the technology and its applications continue to develop.
28. What Blockchain Auditing Could Mean for African Businesses
African businesses are increasingly using digital payment systems, cloud accounting, mobile money and digital financial platforms.
That creates large volumes of digital transaction data.
Blockchain could add another layer of trust and traceability to some of these systems.
For example, a financial platform could record important transactions in a blockchain-backed audit trail.
An auditor could then access a more structured history of those activities.
This could be particularly useful for:
- SACCOs
- Chamas
- Cooperatives
- Banks
- Insurance companies
- Fintechs
- Supply-chain businesses
- Digital asset companies
The technology should still be introduced according to the organisation’s needs.
Not every business needs a blockchain audit system.
MUIAA’s approach to blockchain is centred on practical financial applications.
ChamaConnect is one example.
The platform is designed to help savings groups and SACCOs manage activities such as membership, contributions, savings, loans, welfare and financial reporting.
Behind the user-facing system, blockchain-backed infrastructure can support the integrity and traceability of key transactions.
That creates an important connection between blockchain and auditing.
The objective isn’t to make members interact with complicated blockchain technology.
The objective is to create better financial infrastructure where records can be tracked, important actions can be logged and transaction histories can support stronger accountability.
This is the direction blockchain auditing needs to take.
The technology should make the evidence stronger without making the financial system harder for ordinary users to operate.
30. The Future of Blockchain Auditing
The future of auditing is likely to involve more connected systems.
Blockchain could provide trusted transaction records.
AI could analyse those records.
Smart contracts could automate predefined controls.
Digital identity could establish who performed an action.
Cloud accounting systems could connect financial records.
Auditors could then spend less time collecting basic transaction information and more time interpreting risks and investigating exceptions.
This could move auditing toward a model where assurance happens throughout the financial lifecycle rather than mainly after the reporting period.
But the human auditor remains important.
Someone still needs to understand the business, assess evidence, challenge assumptions and exercise professional judgment.
31. Frequently Asked Questions About Blockchain Auditing
31a. What is blockchain auditing?
Blockchain auditing is the use of blockchain-based records and technology as part of auditing and assurance processes.
31b. How is blockchain used in auditing?
Blockchain can provide traceable transaction records, support audit evidence, reduce some reconciliation work, enable automated controls and create opportunities for continuous monitoring.
31c. Does blockchain eliminate the need for auditors?
No. Auditors still need professional judgment, external evidence and an understanding of accounting, controls and business risks.
31d. Can blockchain prevent fraud?
It can make some forms of record manipulation more difficult, but it cannot eliminate fraud. False or fraudulent information can still be entered into a blockchain.
31e. How does blockchain improve audit trails?
Blockchain can create time-stamped and cryptographically linked records that make changes to historical records difficult without detection.
31f. Can blockchain enable continuous auditing?
It can support more continuous auditing by making transaction information available closer to the time transactions occur. (IFAC)
31g. What are the biggest limitations of blockchain auditing?
Important limitations include inaccurate source data, privacy, scalability, interoperability, smart-contract risks, key management and regulatory uncertainty. (Frontiers)
31h. Can auditors audit cryptocurrency transactions?
Yes. Auditors can examine blockchain transaction histories, but they also need to assess issues such as ownership, wallet controls, data extraction methods and the relationship between blockchain records and financial statements. (ICAEW)
31i. What are smart contracts in blockchain auditing?
Smart contracts are blockchain-based programs that automatically execute predefined rules. Auditors may need to assess their code, controls, permissions and execution.
31j. Is blockchain auditing more secure than traditional auditing?
Blockchain can strengthen certain aspects of transaction integrity and traceability, but it introduces new risks. Security depends on the entire system, including keys, applications, permissions, network governance and external data.
31k. Can blockchain verify real-world information?
Not by itself. Blockchain can preserve information after it is recorded, but additional controls are needed to establish that the original information was accurate.
31l. What is continuous auditing?
Continuous auditing involves using technology and ongoing procedures to monitor and assess transactions and controls throughout the year rather than relying entirely on periodic audit testing.
31m. Will AI and blockchain change auditing?
They can. Blockchain can provide structured transaction histories while AI can analyse large datasets and identify unusual patterns. Human auditors remain responsible for interpretation and professional judgment.
People Also Search For
- blockchain auditing
- blockchain audit
- how blockchain is used in auditing
- blockchain in auditing
- blockchain audit trail
- blockchain accounting and auditing
- blockchain technology in auditing
- blockchain for auditors
- blockchain audit process
- blockchain audit evidence
- blockchain continuous auditing
- blockchain and financial auditing
- blockchain fraud detection
- blockchain audit trail
- smart contracts and auditing
- blockchain auditing risks
- blockchain auditing benefits
- blockchain auditing challenges
- digital audit systems
- blockchain financial audit
- auditing blockchain transactions
- cryptocurrency auditing
- blockchain audit in Kenya
- blockchain in accounting
- distributed ledger auditing
Conclusion
Auditing is built around evidence.
The better the evidence, the easier it is for auditors to establish what happened, when it happened and whether the financial records can be trusted.
Blockchain can strengthen that evidence by creating shared, traceable and difficult-to-alter transaction records.
It can reduce some reconciliation work, support continuous monitoring, automate selected controls and give auditors faster access to transaction histories.
But blockchain doesn’t create truth by itself.
A false transaction can still be recorded.
A poorly designed smart contract can still execute.
A stolen private key can still create serious problems.
And an auditor still needs professional judgment.
The real opportunity is therefore not to replace auditing with blockchain.
It is to build better audit infrastructure around reliable digital records.
As businesses across Africa move more of their financial activity into digital systems, this distinction will become increasingly important.
Blockchain can give auditors better evidence.
AI can help them analyse that evidence.
And well-designed digital financial systems can connect the two.
That is where blockchain auditing becomes practical.