
A SACCO can report growing savings and a large loan portfolio while facing serious financial pressure. Members may continue contributing, yet the society could struggle to meet payments if too much money is tied up in overdue loans or its financial obligations are poorly planned.
This is why SACCO financial management requires more than tracking income and expenses. Leaders need to understand liquidity, assess credit risk, monitor financial performance and maintain controls that protect the society’s funds.
In Kenya, the requirements that apply depend on the SACCO’s legal and regulatory status. SASRA publishes prudential, governance and reporting requirements for the SACCOs it supervises, including guidance on risk management and statutory financial returns.
This guide focuses on the financial decisions behind a well-managed SACCO. It explains how leaders can identify financial pressure early, evaluate lending risks, strengthen oversight and use reliable information to make better decisions.
1. What Does SACCO Financial Management Involve?
SACCO financial management is the process of assessing financial risks, planning the use of funds and monitoring whether the society can meet its obligations while serving its members.
Three areas deserve particular attention:
- Liquidity management: ensuring the SACCO can meet payments and other obligations when they fall due.
- Credit risk management: assessing whether borrowers can repay loans and managing the consequences when they do not.
- Financial controls: ensuring transactions and decisions are properly authorised, recorded, reviewed and protected against errors or misuse.
These areas influence one another. Weak loan repayments can reduce available cash. A liquidity shortage can limit new lending or make it harder to meet obligations. Weak controls can allow these problems to go undetected.
The board and management therefore need a connected view of the SACCO’s financial position rather than relying on one report or a single headline figure.
2. Liquidity Management: Can the SACCO Meet Its Obligations?
Liquidity is the ability to meet financial obligations when they become due. For a SACCO, this may involve payments to members, loan disbursements, operating expenses, supplier payments and other commitments, depending on its structure and applicable rules.
A SACCO can have substantial assets and still experience a liquidity problem. Some assets, such as outstanding loans, may not convert into cash quickly enough to meet immediate obligations.
2a. Why Liquidity Problems Develop
Several factors can put pressure on liquidity:
- Loan repayments arrive later than expected.
- Too much money is committed to loans or investments that cannot be accessed quickly.
- Members’ withdrawal or payment needs exceed available funds.
- Large expenses or loan disbursements occur at the same time.
- Management relies on optimistic repayment assumptions.
- Financial information arrives too late to support timely decisions.
Consider a SACCO expecting KSh 4 million in loan repayments over the next month. If a significant portion is overdue, the actual cash received could be much lower. If management has already committed funds to new loans and upcoming expenses, the shortfall can create pressure.
The issue is not simply whether the SACCO expects to receive money. It is whether the money will arrive in time to meet its obligations.
2b. How SACCOs Can Improve Liquidity Planning
Liquidity management should combine forecasts with regular monitoring.
A SACCO can start by preparing a cash-flow forecast that lists expected inflows and outflows over a defined period. It should compare actual receipts and payments with the forecast and investigate significant differences.
Useful practices include:
- Estimating loan repayments conservatively, particularly for accounts in arrears.
- Identifying large upcoming payments and commitments.
- Monitoring the availability and timing of funds.
- Reviewing the maturity and liquidity of investments.
- Assessing how changes in repayments or member activity could affect cash needs.
- Maintaining appropriate liquidity buffers in line with the SACCO’s risk profile and applicable requirements.
The forecast should be updated when circumstances change. A missed repayment, an unexpected expense or a large withdrawal can alter the SACCO’s short-term position.
For regulated SACCOs, management must also understand the applicable prudential liquidity requirements. SASRA publishes regulatory return forms that include liquidity reporting for deposit-taking SACCOs. The relevant requirements should be checked against the SACCO’s current regulatory category and rules.
3. Credit Risk Management: Can Borrowers Repay?
Credit risk is the possibility that a borrower will fail to meet the agreed repayment terms. It is one of the central risks facing a SACCO that lends to members.
Every loan creates an obligation for the borrower and a financial exposure for the society. A strong credit process considers the risk before disbursement and continues monitoring the loan throughout its life.
3a. Assessing Borrowers Before Approval
A SACCO should evaluate whether a borrower can reasonably repay the proposed loan under the agreed terms.
The assessment may consider income, existing debts, repayment history, loan purpose, savings, guarantors or collateral, depending on the product and applicable policy.
A member’s savings history can provide useful context, but it does not automatically prove that the member can afford a larger loan. The SACCO needs to consider the member’s wider repayment capacity and the risks associated with the application.
Kenya’s SACCO regulatory framework includes requirements for written credit policies covering loan procedures, borrower assessment, loan limits, approval levels, security and guarantees, where applicable. The specific rules depend on the relevant regulations and SACCO category.
3b. Managing Loan Concentration
A SACCO can face additional risk when too much of its lending is exposed to one borrower, employer, industry, geographic area or economic activity.
For example, a SACCO serving members from one employer may experience widespread repayment problems if that employer delays salaries or reduces its workforce.
Concentration limits and portfolio reviews help management understand whether the society is overly dependent on a narrow group of borrowers or sources of income.
The right limits depend on the SACCO’s circumstances and applicable requirements. Management should not wait for defaults to increase before examining how lending is distributed.
3c. Tracking Loan Quality
Loan quality describes how well the loan portfolio is performing and the level of risk associated with outstanding credit.
Management should review indicators such as:
- Outstanding loan balances.
- Repayments received against scheduled amounts.
- Overdue instalments and arrears.
- Loans requiring restructuring or recovery action.
- Concentration by borrower, employer or sector.
- Changes in the proportion of loans that are not performing as expected.
These measures need consistent definitions and reliable source data. Comparing periods is useful only when the underlying calculations and classifications are applied consistently.
A rise in arrears should prompt investigation. It may reflect individual borrower difficulties, weak collection processes, lending decisions that need review or a wider economic problem affecting members.
3d. Managing Guarantor and Security Risk
Where a SACCO relies on guarantors or collateral, management should understand the limits of that protection.
A guarantee does not mean a loan carries no risk. The guarantor may have limited capacity to meet the obligation, may already have guaranteed other loans or may dispute the terms of the guarantee.
The SACCO should document guarantees, apply its approved procedures, monitor relevant commitments and maintain accurate records of any changes or releases.
Security and guarantees should form part of a broader credit assessment, not replace an assessment of the borrower’s ability to repay.
4. Managing Loan Arrears Before They Become Larger Problems
Loan arrears arise when a borrower has not paid an amount by the agreed due date. Unresolved arrears can affect cash flow, loan portfolio quality and the SACCO’s ability to lend to other members.
A practical arrears process should identify overdue accounts early and assign responsibility for follow-up.
4a. Use Consistent Arrears Reports
Management should be able to identify which loans are overdue, the amounts involved, how long payments have been outstanding and what action has been taken.
Reports should distinguish between a recent missed instalment and a loan that has remained overdue for a much longer period. Those situations may require different responses.
4b. Investigate the Cause
A borrower may have missed a payment because of delayed salary, a temporary emergency, reduced business income or a more serious inability to repay.
Understanding the cause helps the SACCO decide what action is appropriate under its policies. It should not assume that every late payment has the same explanation.
4c. Document Recovery Actions
Follow-up communications, repayment arrangements, notices and approved restructuring decisions should be documented.
A clear record helps different officers understand the history of the account and reduces reliance on informal conversations that may be difficult to verify later.
4d. Review Whether Lending Policies Are Working
Repeated arrears can indicate more than individual borrower problems. Management should examine whether the SACCO’s loan assessment, approval process, repayment terms and monitoring procedures are effective.
SASRA’s governance guidance assigns credit oversight responsibilities to relevant board structures, including reviewing lending practices and ensuring procedures exist to identify and manage problem credits. Applicable governance arrangements should be confirmed for the SACCO concerned. <Cite refs={[“turn544070search29″,”turn544070search0”]}/>
5. Financial Controls: Protecting the SACCO’s Funds
Financial controls are the policies and procedures used to reduce errors, unauthorised activity, misuse of funds and unreliable reporting.
They are important even when a SACCO has experienced staff and a good repayment record. Strong financial performance does not remove the need to verify transactions and monitor how decisions are made.
5a. Separate Financial Responsibilities
Where practical, the same person should not control every stage of a significant transaction.
For example, one officer may prepare a payment request, an authorised official may approve it, and another person may review the transaction during reconciliation.
Smaller SACCOs may not have enough staff to separate every task. In those cases, independent review, documented approvals and appropriate board oversight become especially important.
5b. Define Approval Authority
The SACCO should document who can approve loans, expenses, transfers and other financial commitments, including the limits of each person’s authority.
A transaction should not be approved simply because an officer has access to the system or is familiar with the member involved. It should follow the society’s approved procedures.
5c. Reconcile Financial Records
Reconciliation compares records that should agree, such as the SACCO’s bank records and its own cashbook.
Differences may arise from timing, missing entries, duplicate transactions, incorrect amounts or other errors. They should be investigated and resolved using supporting evidence.
Regular reconciliation helps management detect problems that might otherwise remain hidden in summary reports.
5d. Maintain Traceable Financial Decisions
Significant financial decisions should have a clear record of who approved them, when they were approved and what information supported the decision.
This is particularly important for loans, expenses, changes to repayment terms, write-offs and other decisions that can affect the SACCO’s financial position.
5e. Review Controls Independently
Internal review and audit processes can help assess whether controls are designed appropriately and actually followed.
The review should consider both whether procedures exist and whether they work in practice. A written policy offers limited protection if transactions routinely bypass it.
SASRA’s governance guidance discusses internal controls, audit oversight and the responsibilities of relevant committees within regulated SACCOs. The structure and obligations applicable to each SACCO should be verified against its governing framework.
6. Financial Performance: Understanding What the Numbers Mean
Financial reports provide evidence about the SACCO’s position and performance. Their value depends on how well leaders interpret the information and act on it.
A report showing higher income may appear encouraging, but it does not tell the full story on its own. Management should also consider expenses, loan quality, available cash, obligations and changes in the SACCO’s overall financial position.
6a. Review the Statement of Financial Position
The statement of financial position shows assets, liabilities and equity at a particular date.
It helps management understand what the SACCO owns or is owed, what obligations it has and how its financial position is funded.
The report should be considered alongside the liquidity position and the quality of its assets. An outstanding loan is an asset on the books, but its value to the SACCO depends partly on whether it is likely to be repaid.
6b. Review Income and Expenditure
The income statement, also called the statement of comprehensive income under relevant reporting frameworks, shows income and expenses over a period.
Management should compare actual results with the budget and previous periods, investigate material changes and understand the reasons behind them.
Higher income may be accompanied by higher costs or greater credit risk. A useful review looks beyond one favourable figure.
6c. Monitor Financial Indicators Together
No single indicator provides a complete picture of financial health.
| Area | What to examine | What it may reveal |
|---|---|---|
| Liquidity | Available funds, expected inflows and upcoming obligations | Whether the SACCO may face pressure meeting payments |
| Credit quality | Arrears, overdue balances and loan performance | Whether borrowers are repaying as expected |
| Income and expenses | Actual results against budget and previous periods | Changes in operating performance |
| Concentration risk | Exposure to large borrowers or connected groups | Dependence on a narrow part of the loan portfolio |
| Financial controls | Reconciliation differences, exceptions and overdue reviews | Weaknesses in procedures or oversight |
| Reporting quality | Timeliness, accuracy and consistency of reports | Whether leaders can rely on the information |
For regulated SACCOs, some measures are subject to formal definitions, thresholds and reporting rules. Management should use the applicable regulatory guidance rather than assuming that an informal management metric is equivalent to a statutory measure.
7. Financial Planning and Stress Testing
Financial planning helps a SACCO consider how its position might change under different conditions.
A forecast based only on expected results may miss important risks. Management should also consider plausible adverse scenarios, such as slower loan repayments, an increase in member withdrawals where applicable, unexpected expenses or a reduction in income.
7a. Test the Effect of Lower Repayments
Management can estimate how the cash position would change if loan repayments fell below forecast.
For example, if the SACCO expects KSh 2 million in repayments over a month, it could model a scenario in which only KSh 1.5 million arrives. It should then assess whether available funds and other expected receipts are sufficient to meet planned obligations.
This is an illustrative planning exercise, not a regulatory threshold. Each SACCO should use assumptions appropriate to its own portfolio and cash-flow pattern.
7b. Examine Large Commitments
Before making a large loan disbursement, investment or operational commitment, management should consider the effect on available funds and other obligations.
The decision should account for timing, uncertainty and the possibility that expected receipts may be delayed.
7c. Assign Actions to the Findings
A stress test is useful only if the results inform decisions.
If a scenario reveals a possible shortfall, management should identify the available responses, the person responsible for evaluating them and the point at which the issue should be escalated.
This process helps the SACCO prepare before pressure becomes an immediate problem.
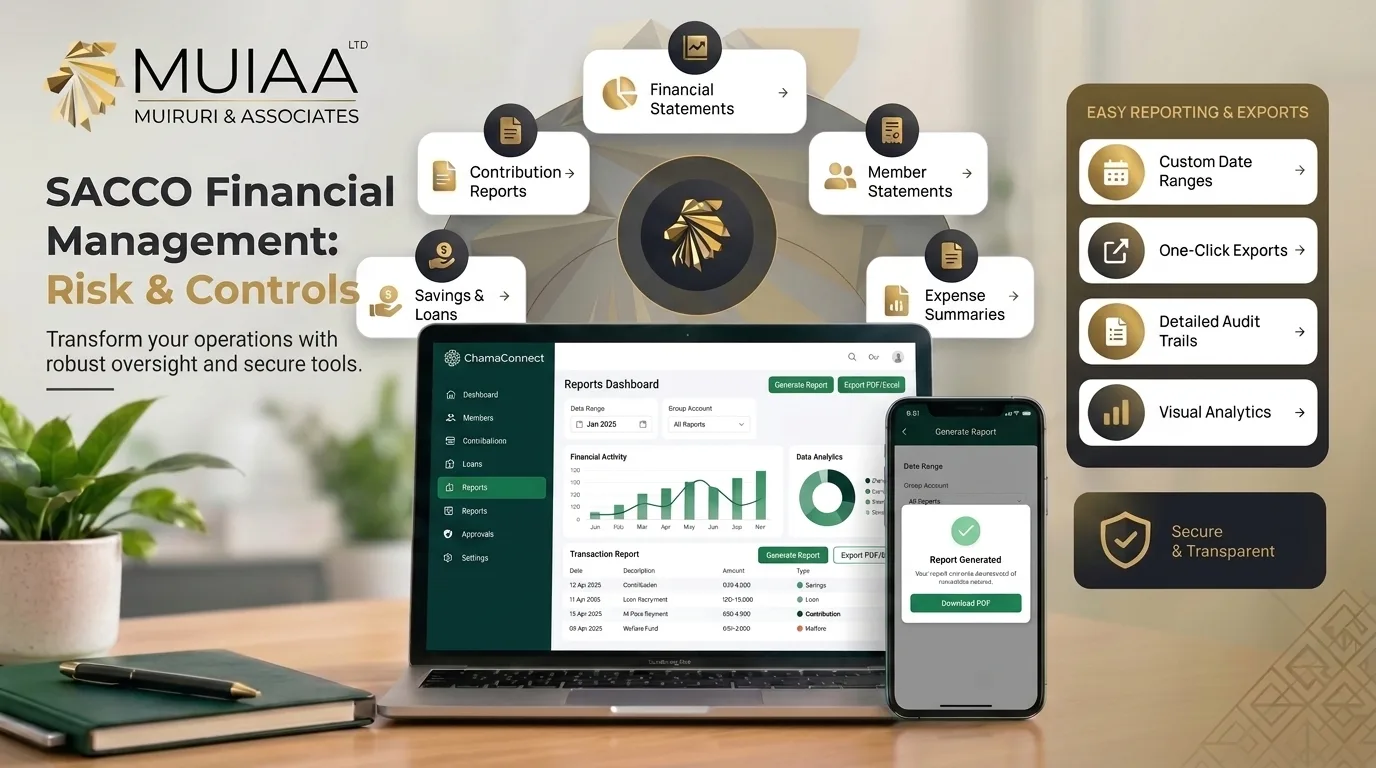
8. How Digital Systems Support Financial Risk Management
Digital systems can improve the timeliness and consistency of financial information when they are configured to reflect the SACCO’s actual processes.
For example, a system that connects loan accounts, repayment schedules and payment records can help management identify overdue instalments without manually comparing several disconnected files.
Digital tools may also support:
- Monitoring loan performance and arrears.
- Producing financial and management reports.
- Recording transaction approvals.
- Identifying discrepancies for review.
- Restricting financial actions by user role.
- Maintaining activity records for investigation.
- Preparing data for reconciliation and audit.
The exact benefits depend on the system’s capabilities, data quality and implementation. A dashboard cannot compensate for inaccurate opening balances or missing transactions. Automated calculations also need to be checked and governed appropriately.
Before adopting a system, SACCO leaders should assess its security, reporting, auditability, backup processes, integration options and ability to export records for independent review. They should also verify that it supports their accounting and regulatory requirements.
9. Can Blockchain Help Strengthen Financial Controls?
Blockchain can support selected financial processes by maintaining a tamper-evident history of transactions or changes. This can help authorised reviewers trace activity and investigate disputes.
For example, a properly designed blockchain-backed system may help establish that a transaction record existed at a particular point and whether subsequent changes were recorded. Its usefulness depends on what information is captured, who can submit it and how the system is governed.
Blockchain does not establish that the original information was correct. If the wrong amount is entered, a tamper-evident record can preserve evidence of the entry without making the amount accurate.
It also does not replace credit assessment, cash-flow planning, reconciliation, accounting or independent oversight.
MUIAA’s wider blockchain content explores how distributed ledger technology may support SACCO operations, lending and audit processes. These applications should be evaluated against a defined financial or governance problem rather than adopted simply because the technology is available.
Related reading:
- Blockchain for SACCOs: how the technology may support cooperative financial processes.
- Blockchain Loan Management for SACCOs: the potential role of traceable records in lending workflows.
- Blockchain Auditing: how tamper-evident records may support audit evidence and transaction tracing.
- Blockchain Smart Contracts for SACCOs and Banks: how programmable rules may support approved financial workflows.
10. Financial Management and SACCO Regulation in Kenya
Kenyan SACCOs do not all operate under an identical regulatory framework. Obligations depend on the society’s activities, category and applicable laws.
SASRA is responsible for licensing deposit-taking SACCOs and supervising those deposit-taking and specified non-deposit-taking SACCOs that fall within its mandate. The Authority publishes relevant statutes, regulations, prudential guidance and reporting materials.
The SASRA risk management guidelines and governance guidance are useful starting points for understanding risk oversight and financial governance.
SACCO leaders should confirm which requirements apply to their institution and seek qualified professional advice when interpreting regulatory obligations. This article offers general financial management guidance and should not be treated as a complete compliance checklist.
11. A Practical Financial Risk Review for SACCO Leaders
A regular financial review can help a board or management team identify issues that need attention.
The review should cover:
- Whether available funds are sufficient for expected obligations.
- Whether loan repayments are meeting expectations.
- Whether arrears or concentration risks are increasing.
- Whether major expenses and commitments remain within approved limits.
- Whether reconciliations have been completed and differences resolved.
- Whether reports are current and supported by source records.
- Whether significant financial decisions have the required approvals.
- Whether previous review findings have been addressed.
The meeting should produce clear actions, deadlines and responsibilities. Financial reporting becomes more useful when it leads to decisions that can be followed up and evaluated.
12. Frequently Asked Questions
What is the biggest financial risk for a SACCO?
There is no single risk that affects every SACCO in the same way. Common concerns include loan defaults, liquidity pressure, concentration of lending, weak financial controls and unreliable reporting. Their relative importance depends on the SACCO’s portfolio, funding model, operating environment and governance.
What is the difference between liquidity risk and credit risk?
Liquidity risk is the risk that a SACCO cannot meet its obligations when they fall due. Credit risk is the risk that borrowers will not repay as agreed. Poor loan performance can create liquidity pressure, so the two risks are connected.
How can a SACCO reduce loan default risk?
A SACCO can strengthen borrower assessment, apply a written credit policy, monitor loan concentration, track arrears and document recovery actions. Guarantors and collateral may provide additional protection where applicable, but they do not eliminate the need to assess repayment capacity.
Why are internal financial controls important?
Controls help ensure that transactions are authorised, accurately recorded and independently reviewed where appropriate. They can reduce errors, unauthorised activity and the risk that financial problems remain undetected.
What financial reports should SACCO leaders review?
Depending on the SACCO’s structure and requirements, useful reports include the statement of financial position, income statement, cash-flow information, liquidity reports, loan portfolio performance, arrears, budget comparisons and reconciliation results. Regulated SACCOs should also follow the applicable statutory reporting requirements.
Can software prevent SACCO financial mismanagement?
Software can improve visibility, restrict access, automate selected tasks and maintain activity records. It cannot guarantee good management. The SACCO still needs sound policies, accurate data, competent oversight, reconciliation and appropriate approval procedures.
Does blockchain eliminate financial fraud in SACCOs?
No. Blockchain may make selected records more difficult to alter without detection, depending on the design. It cannot independently verify that every original entry is true or prevent all forms of fraud. Effective controls, access management and independent review remain necessary.